TOP STORIES
CARTOONS
MAGIC MONEY TREE
POSH GRAMMAR
OSBORNE KERCHING!!
PROMISES PROMISES
SOUTHERN FAIL
DUMB POLLSTERS
DON'T BLAME TRUMP!
£13bn APPLE TAX DODGE
SAFE SEATS = BREXIT?
UKIP v LABOUR
ALL OUT OF IT TOGETHER
EU IMMIGRATION
TORY v TORY
PRISON SUICIDES
LONDON LEAVES UK!
EU v TORY MANDATE
HMRC IS A TAX HAVEN
PANAMA TAX LEAK
IDS v IDS
RICH v POOR
POSH BOYS
HELP2BUY PROFITEERS
LLOYDS, RBS CEO PAY
HSBC DRUG MONEY
PM'S MUM FIGHTS CUTS
PEAK "STUFF" IS HERE
HMRC GOOGLY
PENSION TAX RAID
Showing posts with label OFT. Show all posts

Friday, 24 April 2015

Friday, April 24, 2015 Posted by Hari No comments Labels: , , , ,
Fee, KJ and Chris shop for answers...

SOURCE GUARDIAN: UK supermarket “deals” dupe shoppers out of hundreds of millions, says Which?
The consumer group Which? claims supermarkets are pushing illusory savings and fooling shoppers into choosing products they might not have bought if they knew the full facts. Examples raised by Which? include Tesco flagging the “special value” of a sweetcorn sixpack when a smaller pack was proportionately cheaper, and Asda raising the individual price of a product in order to make the multi-buy deal more attractive. The cumulative impact of all these different pricing tactics is that it is impossible for people to know if they are getting a fair deal, the consumer group says, particularly when prices vary frequently, consumers are in a hurry or are buying numerous low value items. About 40% of groceries in Britain are currently sold on promotion, according to the retail analysts Kantar Worldpanel. With £115bn spent on groceries and toiletries in 2013, Which? said consumers could be collectively losing out to the tune of hundreds of millions of pounds. This is the first ever super-complaint Which? has lodged against the grocery sector after compiling a dossier of “dodgy multi-buys, shrinking products and baffling sales offers” and sending it to the Competition and Markets Authority. Which? has previously made super-complaints on care homes, credit card interest rates, Northern Ireland banking, private dentistry and the Scottish legal profession.

Saturday, 17 May 2014

Saturday, May 17, 2014 Posted by Jake 1 comment Labels: , , , , , , ,

In May 2014 the energy regulator OFGEM boasted about its latest ‘record fine’: £12 million inflicted on E.on. OFGEM’s press release stated:
  • E.ON’s large scale mis-selling results in biggest supplier payout to consumers 

  • Ofgem found management arrangements were insufficient to protect against mis-selling

OFGEM has the power to fine upto 10% of revenue. E.ON’s UK revenue in 2013 was £9.9 billion. The £12million fine, about 0.1% of revenue, is not even a drop in that ocean of cash.

Money is the one thing that is not in short supply for Energy companies. They are awash with it. Fraudulent behaviour by our Energy and Financial sectors have been ‘punished’ by taking from them that which they have most of: money taken from their customers. Like fining Billy Bunter a doughnut – he may not like it, but he has plenty more. The loss of a doughnut will not reform him.

Fraud is directed by people, not companies. Directors don’t fear fines – after all it is almost inevitably the company that pays them. But while they have more than enough money to brush off fines, they have about the same amount of time as anyone else. A year in jail is a year in jail, whoever you are.

The Sentencing Council, appointed by the Lord Chief Justice and the Lord Chancellor of the UK, provides guidance to the British Justice System. Here is the guidance when it comes to frauds by ordinary citizens:
  • "Confidence Fraud" (not unlike doorstep selling by energy companies) for sums of £500,000 or more: 5-8 years custody 

Friday, 28 March 2014

Friday, March 28, 2014 Posted by Hari No comments Labels: , , ,
Fee, KJ and Chris wonder what will happen next to the "Big 6" energy firms...

Sunday, 12 January 2014

Sunday, January 12, 2014 Posted by Jake 4 comments Labels: , , , , , ,
In January 2014 the Labour Party issued another report, “Powering Britain: One Nation Labour’s plans to reset the energy market”. The report made various assertions relating to the period after 2010, conveniently overlooking Labour’s own lamentable record regulating the energy industry. It is quite extraordinary how much politicians care for us when out of power, and how little when in power. Wasn’t it Spiderman who said “With no responsibility comes great power”. Power to talk without having responsibility to deliver. Anyway, the report stated:


"Since 2010, household energy bills have gone up by over £300 a year whilst small businesses are paying over £13,000 a year more


Lack of competition in the retail market has resulted in consumers paying £3.6 billion more than they need to"


The report includes graphs showing how energy companies’ blaming wholesale cost (what the energy companies pay) for retail price (what you pay) rises since 2011 are phoney. Average annual increases between 2011 and 2013 have been:

  • Electricity: wholesale up 0.5% per year; retail up 9.7% a year
  • Gas: wholesale up 1.59% per year; retail up 11% per year


OFGEM, the energy regulator, denies that consumers are being ripped off though OFGEM accepts the need to “break the stranglehold of the big 6 in the retail market” (so we're not being ripped off, just strangled?) and has repeatedly blamed energy companies for not being "transparent" (i.e. telling the simple truth) about their wholesale costs.

Tuesday, 24 September 2013

Tuesday, September 24, 2013 Posted by Hari No comments Labels: , , , , ,

Sunday, 14 July 2013

Sunday, July 14, 2013 Posted by Jake 2 comments Labels: , , , , , ,
This graph produced by Bristol University's study on high cost lending shows the cost of borrowing £100 for one month in the form of:

a) a loan from a group of Payday lenders
b) an unauthorised overdraft from a group of high street banks
c) an authorised overdraft from a group of high street banks

Bristol University coyly declines to name the payday lenders and high street banks.

Cost of borrowing £100 for one month
However the report does provide a helpful link to Which?, showing the data from 2011, which does name them:

Friday, 1 March 2013

Friday, March 01, 2013 Posted by Hari 3 comments Labels: , , ,
Fee, Chris and KJ hope that's the end of the matter...


Friday, 18 January 2013

Friday, January 18, 2013 Posted by Hari No comments Labels: , , ,
Chris is suspicious...


Tuesday, 1 January 2013

Tuesday, January 01, 2013 Posted by Jake 3 comments Labels: , , ,
We at Ripped-off Britons aim to provide you with well sourced facts and data so you can digest and pass them on by word of mouth, by email, by re-tweeting.

But there's a limit to what we can do. So we invite you to find relevant articles and recommend them to us for publication on our blog.

We ourselves look around for suitable material ourselves, and have already gratefully accepted contributions from a number of guest authors. But there are only so many hours in a day available from our other duties. So we invite you, our readers, to suggest articles you have come across by doing the following:


  • Email us a link to the article, to suggestions@rippedoffbritons.com
  • We will check out the article, to see if it fits in with our campaigning
  • If it does, we will contact the author and invite them to contribute the article to Ripped-off Britons
  • If the author accepts our invitation and we publish the article, we will invite you to select a Ripped-off Britons cartoon of your choice, which we will print and sign and post to you. (Perhaps not as liquid as cash, but it's the only sort of Quantitative Easing we can afford, and a sight less dodgy than the Bank of England's).
The articles we seek need to be more than unsupported assertions. We want evidence to back up the assertions, such as:


  • Quotes from recognised sources
  • Data from respected organisations
  • Well presented graphs and graphics
Campaigners like us are in competition with those who sell their rip-offs. Rip-offs that include dodgy financial products; gouging energy and transport price hikes; mendacious political stances. In this competition, in spite of the overwhelming financial power of advertisers, impecunious campaigners can still punch above our weight. According to a survey by Nielsen (a research company that aims to provide “the most complete understanding of what consumers watch and buy”):

“Although television advertising will remain a primary way marketers connect with audiences due to its unmatched reach compared to other media, consumers around the world continue to see recommendations from friends and online consumer opinions as by far the most credible.”

Which still means us campaigners are at a vast disadvantage, but less vast than you might think. 

The difference, dear reader, is you. People believe you far more than they do a costly advertising campaign or a weasel government statement. In contrast, corporate executives hoping to swipe your money and government ministers hoping for promotion and for private clients for their "cab for hire" services are greeted with the scepticism they deserve.

Sunday, 30 December 2012

Sunday, December 30, 2012 Posted by Jake 3 comments Labels: , , , , , ,
File:Siege perilleux galaad.jpg
http://en.wikipedia.org/wiki/File:Siege_perilleux_galaad.jpg
December 2012 saw a former chief of the Financial Services Authority (Hector Sants) and December 2013 a former deputy governor of the Bank of England (Paul Tucker) knighted. Men whose responsibilities included regulating the banks during the banking crash. They joined the array of lords and knights in the well padded seats of the City of London's financial district.

Every bank, insurance company and investment firm covets a noble or two to adorn its board. What could possibly go wrong if a peer of the realm is at the helm?

It is not just financial services. Lords and ladies, knights and dames grace the boards and regulators of electricity, transport, education, health, and just about every major commercial endeavour. Judge them not by their fruits, but by their titles.

To recognise these valiant men and women who fearlessly take responsibility for our nation's well being, ensuring the good and chivalrous behaviour of their companies and those they regulate. In praise of these goodly citizens who use their bodies, minds and reputations as buttresses against all the unseemly pillaging and ripping-off, we give you an excerpt from Monty Python's tale of Camelot:

Brave Sir Robin ran away.
Bravely ran away, away!
When danger reared its ugly head,
He bravely turned his tail and fled.
Yes, brave Sir Robin turned about
And gallantly he chickened out.
Bravely taking to his feet
He beat a very brave retreat,
Bravest of the brave, Sir Robin!

Sunday, 2 December 2012

Sunday, December 02, 2012 Posted by Jake 3 comments Labels: , , , , , ,
In January 2012 the Office of Fair Trading (OFT) launched an investigation on “Retail food pricing and promotional practices”. The investigation was closed on 30th November 2012, when  the OFT courageously announced
“The OFT has made no finding that the supermarkets have breached the law or were engaging in misleading promotional practices.”
That the supermarkets did not breach the law is not a surprise. British consumer protection law in the form of the “Consumer Protection from Unfair Trading Regulations” is a charter for rip-offs. The law explicitly states that deception is perfectly legal so long as it only deceives the less than average consumer. 


Incredibly it is also explicitly legal under this law for a trader to knowingly engage “in a commercial practice which contravenes the requirements of professional diligence” so long as his actions are not “likely to materially distort the economic behaviour of the average consumer with regard to the product under regulation”.  Blimey! 

But while the law only protects the more than average half of Britons, the Office of Fair Trading provides detailed guidance so even the most brutishly stupid retailer will understand how to skirt around consumer protection law if he is so inclined. A kind of 'no retailer left behind' scam tutorial.

To help the dimmer retailers OFT's guidance provides pictures to make sure retailers don't need a moral compass to navigate the law. The law identifies 31 practices that are banned under all circumstance. But apart from those 31, anything goes so long as it only hits the 'less than average'.


Although the above graphic from the OFT's "Guidance on  the Consumer  Protection from Unfair Trading  Regulations  2008" states that it is "Unfair if they cause consumers to take a different decision", the law itself clarifies that this only protects the "average" consumer as stated in these extracts from the legislation: 

Saturday, 6 October 2012

Saturday, October 06, 2012 Posted by Hari No comments Labels: , , , ,
Chris and his wife find out the hard way...

Wednesday, 18 July 2012

Wednesday, July 18, 2012 Posted by Hari No comments Labels: , , , , ,
KJ sticks to the oldest sales trick in the book...

Tuesday, 21 February 2012

Tuesday, February 21, 2012 Posted by Hari No comments Labels: , , , , , , ,
Chris and KJ discuss bonuses and PPI losses at Lloyds Bank

Friday, 27 January 2012

Friday, January 27, 2012 Posted by Hari No comments Labels: , , , , ,
Fee takes a stand against a local gym, after LA Fitness did a u-turn after public pressure

Friday, 9 December 2011

Friday, December 09, 2011 Posted by Hari No comments Labels: , , , ,
KJ and his father weigh up private healthcare over NHS treatment

Sunday, 6 November 2011

Sunday, November 06, 2011 Posted by Jake 3 comments Labels: , , , , , , , ,
Ripped-off Britons
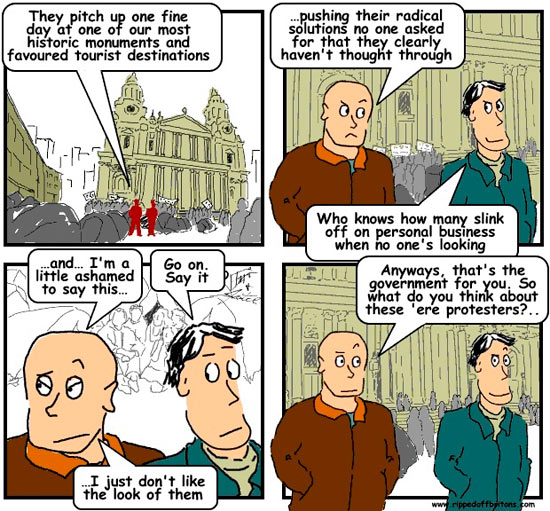
So the Church lifted its threat to send in large padded men to throw the campers out, and the protest outside St. Paul’s Cathedral in London continued. In a conversion on the road to the High Court worthy of St. Paul himself, the clergy suddenly realised “what Jesus would do” if he were physically, as well as spiritually, in the Cathedral. Jesus would be applying the toe of his physical sandal to their highly embroidered clerical backsides. Who were the greater malefactors when Jesus threw the money lenders out of the temple in Jerusalem? The moneymen, who were suckering customers with every rip-off man’s laws and the regulators permitted? Or the priests who succoured the moneymen?


This blog has repeatedly stated: deal with the excessive profits and the bonuses will deal with themselves. For Ripped-Off Britons to be less ripped off, the amount of the bankers’ bonus in itself is irrelevant. It is the rip-offs that pay for the bonuses that are the problem.

Blocking bankers' bonuses can easily be dismissed as being envy driven. On the other hand, reducing rip-off profits is just good sense. Bankers will argue that their profits aren’t rip-offs, but are the fruits of their being extremely clever and courageous. The hilarious speech by Bob Diamond, the boss of Barclays Bank, on the BBC is a good example of what they want us to believe. Having said in January 2011 that the “period for remorse and apology” was over, his latest position is “we have to accept responsibility for what has gone wrong". “We know it's not enough just to apologise” says uncle Bob. 

Diamond pointed out that banks provide an important service, including putting together a pool of investors who can lend money to, among others, governments to service their debt. He said that government debt as a proportion of GDP is


He didn’t need to look back 10 years, 3 years would have been enough as the debt more than tripled in 2008 at one of the heights of the banking crisis, because governments borrowed money to bail out the banks. And the banks now make handsome profits lending money to governments to cover the loans taken by governments to bail out the banks.


 Diamond went on to talk about the people he had met, including

  • When I was in Yorkshire earlier this year, I met R&R Ice Cream. R&R Ice Cream started as a small family business...
  • I also met with Swann Morton in Sheffield, the home of steel manufacturing. They began in the 1930s making razor blades for the UK.
  • Sukhpal Singh is an entrepreneur I met in Cambridge who came here as a refugee from Uganda in the 1970s. At the age of 18 he borrowed £5,000 - from his father and from a local bank - to buy a car parts shop in North London.

In the post-speech interview with BBC Radio4’s John Humphrys, Diamond said that Bankers can be cuddly. So lets take a closer look at how cuddly they are, in an area where just about every one of us is affected – our bank accounts.

With Which?, the organisation championing consumers, and the ironically named Financial Services Authority (FSA), whose purpose has never been clear, highlighting potential problems with Packaged Current Accounts, we shall look more generally at personal bank accounts which earn the banks £billions in charges. (The FSA’s hyperactivity in the final months before its abolition is akin to a drunken uncle who having disgraced himself at dinner insists on doing the washing up to try and leave behind a more positive memory.) We shall see whether the £billions of profits are the rewards of being extremely clever and cuddly, or just the proceeds of thuggish muggings.

Wednesday, 26 October 2011

Wednesday, October 26, 2011 Posted by Hari No comments Labels: , , , , , , , ,
Chris and his wife try and find the best bargains while shopping in a supermarket

Sunday, 23 October 2011

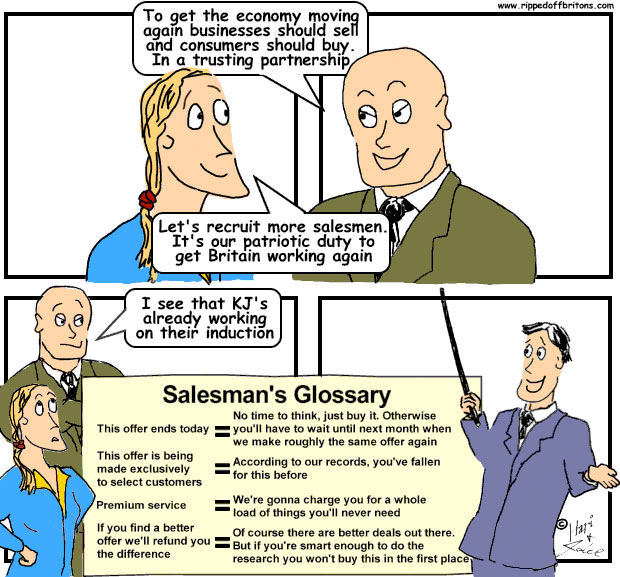
Ripped-off Britons: Sales speak explainedThe right to rip-off Britons is enshrined in British law, most explicitly by the ironically named “Consumer Protection from Unfair Trading Regulations”. It is not our contention that the rip-offs we write about in this blog are illegal – just that they are rip-offs. But that is the problem: as you will read in the rest of this blog, the rip-offs are not in breach of the Consumer Protection from Unfair Trading Regulations so long as they rip-off no more than half their target market.


The preamble in this legislation tells us that the law will protect the “average consumer” (and of course all those smarter or better informed than average). It helpfully goes on to qualify this “average consumer” as being “reasonably well informed, reasonably observant and circumspect”.


It further states that:
“In determining the effect of a commercial practice on the average consumer where the practice is directed to a particular group of consumers, a reference to the average consumer shall be read as referring to the average member of that group.”

...going on to say:

“(a) where a clearly identifiable group of consumers is particularly vulnerable to the practice or the underlying product because of their mental or physical infirmity, age or credulity in a way which the trader could reasonably be expected to foresee,

and


(b) where the practice is likely to materially distort the economic behaviour only of that group,

a reference to the average consumer shall be read as referring to the average member of that group”

Thus, in words comprehensible to the average trader, the legislation makes clear that the trader is permitted to rip off the "below average" half of the population. If the trader, be he a high-street banker or a purveyor of sweeties, is selling specifically to a mentally infirm or credulous group then he is permitted to rip off the more infirm and credulous half of the group.

The act goes on to stipulate explicitly what a trader may and may not do:

  • A commercial practice is unfair if…..it materially distorts or is likely to materially distort the economic behaviour of the average consumer with regard to the product. 
  • A commercial practice is a misleading action if…. it causes or is likely to cause the average consumer to take a transactional decision he would not have taken otherwise. 
  • A commercial practice is a misleading omission if, in its factual context…. it causes or is likely to cause the average consumer to take a transactional decision he would not have taken otherwise. 
  • A commercial practice is aggressive if….it significantly impairs or is likely significantly to impair the average consumer’s freedom of choice or conduct in relation to the product concerned through the use of harassment, coercion or undue influence


The act continues that a trader is guilty of an offence if:
  • (a) he knowingly or recklessly engages in a commercial practice which contravenes the requirements of professional diligence under regulation 3(3)(a);
and
  • (b) the practice materially distorts or is likely to materially distort the economic behaviour of the average consumer with regard to the product under regulation 3(3)(b).

Never underestimate the power of an “and”. Einstein, in one of his quips about the world we live in, thought compound interest was the most powerful force in the universe. I think it is “and”, and/or perhaps “or”. Two little words that make almost anything possible. In this case the “and” tells us that the trader is legally allowed to use any tactic he wants, be it unfair, misleading, aggressive, reckless, unprofessional so long as the “average consumer” won’t be tricked by them. Anyone “less than average” is fair game to be recklessly coerced, misled, and handled unfairly. On them it’s open season 12 months a year!


To understand the implications of the legislation:

Tuesday, 27 September 2011

Tuesday, September 27, 2011 Posted by Hari No comments Labels: , , , , , , , , , ,
Labour reinvent the wheel in the name of consumer rights

Share This

Follow Us

  • Subscribe via Email

Search Us